 ADAD
Updating your news feed...
NEWS EXPRESS is Nigeria’s leading online newspaper. Published by Africa’s international award-winning journalist, Mr. Isaac Umunna, NEWS EXPRESS is Nigeria’s first truly professional online daily newspaper. It is published from Lagos, Nigeria’s economic and media hub, and has a provision for occasional special print editions. Thanks to our vast network of sources and dedicated team of professional journalists and contributors spread across Nigeria and overseas, NEWS EXPRESS has become synonymous with newsbreaks and exclusive stories from around the world.
.webp)
Loading banners
Loading banners...
The National Insurance Commission (NAICOM) has warned that Nigerian insurance companies could remain vulnerable to financial failure, even after completing their recapitalisation, if their boards fail to strengthen corporate governance, improve risk management and ensure the prudent use of shareholders’ funds.
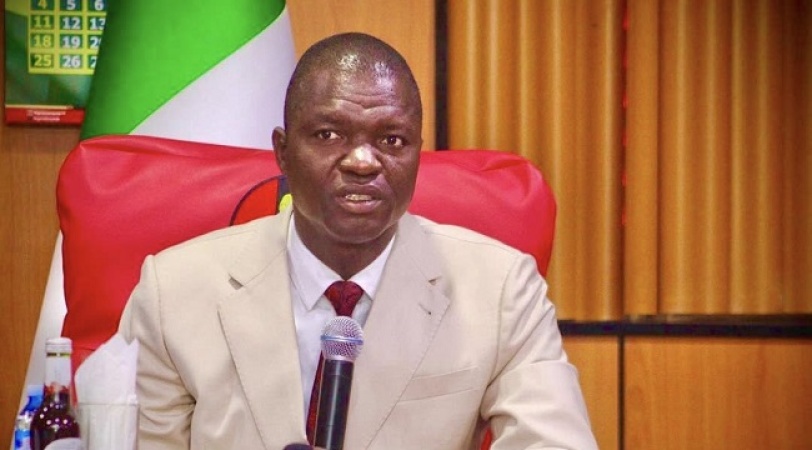
The Commissioner for Insurance and Chief Executive of NAICOM, Olusegun Ayo Omosehin, said the successful completion of recapitalisation was only the beginning of a more demanding phase for the industry, requiring insurance companies to demonstrate their ability to manage risks, protect capital and meet their obligations to policyholders.
He said an insurance company’s strength should no longer be measured mainly by the amount of capital it has raised, but by how effectively it manages, invests and protects that money against financial and operational risks.
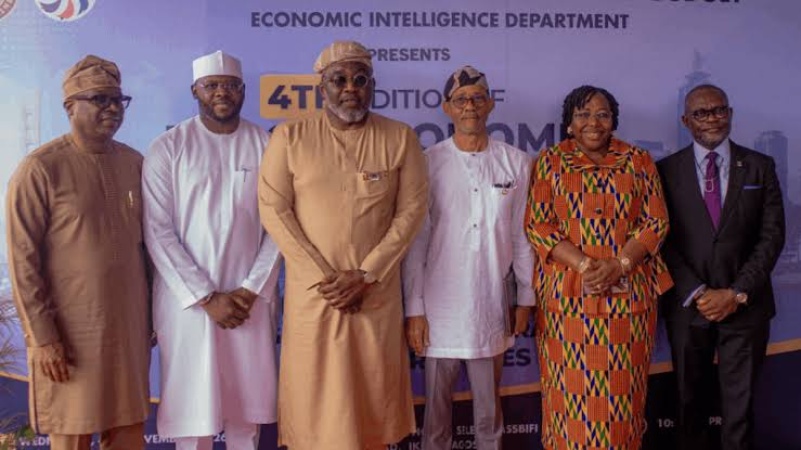
Omosehin spoke at the eighth Annual Insurance Directors’ Conference, organised by the College of Insurance and Financial Management in collaboration with NAICOM, in Lagos on Thursday. The conference theme was ‘Recapitalisation to Resilience: Leading the Risk-Based Capital Era’.
According to him, the industry must move beyond meeting the new capital requirements and concentrate on building financially sound institutions capable of surviving economic shocks, technological disruptions and other emerging risks.
He said, “Recapitalisation was never the destination; it is the gateway to a more demanding phase — a phase that will be defined not by the size of capital alone, but by how that capital is governed, protected, deployed and aligned with risk.”
The commissioner warned that having substantial financial resources did not automatically make an insurance company financially secure, noting that poor governance, weak internal controls, inappropriate investments and ineffective risk management could undermine even well-capitalised institutions. “A well-capitalised institution is not necessarily a resilient institution,” he said.
He explained that true resilience meant having the capacity to identify potential threats, withstand financial shocks, adjust to changing business conditions, recover from disruptions and continue providing value to customers and other stakeholders.
Omosehin said the transition to the Risk-Based Capital (RBC) framework would change how insurance companies are assessed and supervised, as the regulator would increasingly examine the risks each institution undertakes and whether its capital is sufficient to support those exposures.
He explained that the Minimum Capital Requirement (MCR) sets the minimum capital an insurance company must maintain to operate its licensed business, while Risk-Based Capital goes further by assessing the risks the institution carries and the additional capital needed to support them.
Under the new supervisory approach, an insurance company could meet the prescribed minimum capital requirement but still have inadequate capital relative to the nature, size, and complexity of its business risks.
He said this distinction was central to the new regulatory framework because companies with different business operations and risk exposures could not be assessed solely on their minimum capital levels.
The commissioner said NAICOM would pay greater attention to the quality of capital, risk management systems, corporate governance, financial reporting, and the ability of insurance companies to meet claims and other obligations.
He warned that completing recapitalisation would not exempt insurance companies from continuous regulatory supervision. “Successful recapitalisation does not confer permanent immunity from regulatory scrutiny. Capital adequacy is a continuous responsibility,” Omosehin said.
He added that insurance companies must maintain accurate financial records and submit complete, reliable and timely information to the commission to enable the regulator to assess their actual financial and operational positions.
The commissioner also called on directors to take greater responsibility for managing and protecting the capital raised during the recapitalisation exercise.
He said the traditional practice of boards merely receiving management reports without sufficiently questioning decisions must give way to more active supervision.
According to him, directors must challenge management assumptions, examine business strategies and ensure that major decisions are supported by reliable information and sound judgement.
He said boards must ensure that companies’ expansion plans were realistic and consistent with their financial strength, business models and capacity to manage risks.
Omosehin said directors must also prevent capital from being depleted through poor underwriting decisions, excessive operating expenses, inappropriate investments and uncontrolled business expansion.
He urged boards to make capital management a continuous responsibility rather than leaving it to finance departments or waiting for periodic regulatory examinations.
On risk management, he said insurance company boards must set clear limits on the risks their institutions can accept and regularly assess their exposure to underwriting losses, reinsurance arrangements, investment risks, liquidity challenges, technology-related threats and other operational vulnerabilities.
He also called for stronger internal audit, compliance, risk management and actuarial departments, saying these units must have the resources, independence and authority required to identify weaknesses and report them directly to appropriate board committees.
The commissioner said boards must also ensure that their members possess the professional knowledge required to supervise increasingly complex insurance businesses.
He listed insurance, finance, actuarial science, law, investment management, technology and risk management among the areas of expertise that should be represented in insurance company boardrooms.
He said directors must also undergo continuous professional development to keep up with industry changes and emerging business risks.
Omosehin cautioned that board appointments should not be treated as honorary positions, adding that directors have important fiduciary, professional and regulatory responsibilities.
“Board membership is not an honorary appointment. It is a position of trust that carries significant fiduciary, professional and regulatory obligations,” he said.
The commissioner also warned against allowing shareholders’ expectations for higher returns to undermine the financial stability of insurance companies.
He said although investors who provided additional capital had legitimate expectations of growth and returns, these interests must be balanced against insurers’ obligations to policyholders, creditors, employees, regulators and the wider public.
According to him, boards must retain their independence and resist shareholder pressure to pursue aggressive business strategies that could expose companies to excessive risks.
He said executive management must also be held accountable for the prudent use of company resources, business performance, compliance with regulations and the implementation of strategies approved by the board.
Omosehin identified changing risks in the global insurance market as another reason companies must strengthen their financial and operational capacity.
He said climate-related disasters were becoming more frequent and severe, while cyber threats, technological changes, economic volatility and geopolitical developments were creating new challenges for insurance businesses.
He added that changing consumer expectations were pressuring insurers to provide faster services, more personalised products, greater transparency, and improved digital experiences.
According to him, policyholders increasingly expect insurance companies to honour their contractual obligations promptly when claims arise.
He said insurance companies must therefore become more innovative, technologically equipped and responsive to customers if they are to remain competitive and financially sustainable.
On the economic importance of the recapitalisation exercise, the commissioner said a stronger insurance industry could better support Nigeria’s infrastructure, energy, manufacturing, agriculture and construction sectors.
He explained that businesses in these sectors need dependable insurance protection to manage risks and attract investment.
He said a financially stronger industry would also improve Nigeria’s ability to retain more risks locally instead of depending heavily on foreign insurance markets.
Omosehin added that insurance companies could become more important sources of long-term investment funds for the country’s financial markets and productive sectors.
He said the increased financial capacity of insurance companies should also translate into wider insurance coverage, more affordable products and improved access to financial protection for Nigerians.
However, he cautioned that these benefits would not happen automatically, urging insurance companies to develop products that meet the needs of businesses and households, improve service delivery and settle genuine claims promptly and fairly.
Omosehin said the public would ultimately judge insurance companies not by the size of their capital but by their willingness and ability to fulfil their promises when policyholders suffer losses. “At the centre of the insurance business is a promise: the promise to provide financial protection when an insured event occurs,” he said.
The commissioner urged directors to make policyholder protection central to their companies’ business strategies, noting that claims settlement remained one of the most important factors shaping public confidence in the industry.
He also called on insurance companies to strengthen compliance with NAICOM’s Fit and Proper requirements for directors, chief executives and other senior management personnel.
He said appointments to board and management positions should be based on competence, experience, integrity, professional qualifications and financial soundness rather than personal relationships, influence or social status.
According to him, boards must regularly assess and document whether their directors and senior executives continue to meet the required standards throughout their tenure.
Omosehin said the post-recapitalisation period offered the industry an opportunity to improve financial stability, attract investors, strengthen public confidence and become a more important contributor to national economic development.
He challenged insurance company directors to ensure that the additional capital raised during the exercise resulted in stronger underwriting capacity, improved risk management, better claims settlement and sustainable business growth.
He urged them to consider whether their institutions had become genuinely stronger after recapitalisation, whether their boards could effectively challenge management decisions and whether the capital raised was being deployed in ways that would improve their long-term performance.
He said Directors’ decisions would determine whether the gains of recapitalisation were sustained and whether the industry could earn Nigerians’ confidence.
The commissioner urged conference participants to make the post-recapitalisation era a turning point for the industry, rather than a period remembered only for the additional funds insurance companies raised. (The Nation)